US services activity continued to expand, although the main surveys gave differing signals on momentum. The S&P Global Services PMI rose to 58.8 from 56.5, its strongest reading since July 2021, while the ISM measure eased to 54.9 from 55.4. Fed minutes indicated that most officials still saw another rate hike as likely appropriate by year-end.
Elsewhere, services activity strengthened across Europe, with Eurozone private-sector growth reaching its strongest pace in nearly three and a half years. UK activity also improved, with the Composite PMI rising to 54.4, signalling the fastest growth in six months. The Reserve Bank of India raised rates by 25bps to 5.50% and adopted a “calibrated tightening” stance, signalling a greater focus on containing rising inflation pressures.
Last week's highlights
 |
- S&P Global Services PMI (05/10) - US services activity accelerated sharply in September, with the PMI rising to 58.8 from 56.5, the strongest expansion in the sector since July 2021.
- ISM Services PMI (05/10) - eased to 54.9 in September from 55.4, US services sector continued to expand, but at a slightly slower pace than in the previous month.
- FOMC Meeting Minutes (07/10) - Most officials saw another rate hike as likely appropriate by year-end.
|
 |
- HCOB Eurozone Services PMI (05/10) – Eurozone services activity rose to 53.0 in September from 51.6, a 10-month high, signaling strong growth across the bloc.
- HCOB Eurozone Composite PMI (05/10) – Rose to 53.1 in September from 52.0, the strongest pace of private-sector growth in nearly three and a half years.
|
 |
- S&P Global Services PMI (05/10) – The US Services PMI rose to 54.9 in September from 53.9, signalling a solid pickup in activity across the services sector.
- S&P Global Composite PMI (05/10) – Rose to 54.4 in September from 53.4, the fastest pace of private-sector growth in six months.
|
 |
- Reserve Bank of India Meeting (07/10) - The RBI raised the repo rate by 25bps to 5.50% and shifted its policy stance to “calibrated tightening”, signalling a greater focus on containing rising inflation pressures.
|
Looking ahead, US CPI will be a key focus, as investors assess the outlook for inflation and Fed policy, alongside retail sales and producer prices. European inflation and industrial production data, UK growth figures and the start of US earnings season will also be in focus.
What's on the radar
|
- CPI – September (14/10)
- Retail Sales MoM (15/10)
- PPI – September (15/10)
|
|
- Eurozone Industrial Production (15/10)
- German CPI (13/10)
- CPI YoY (16/10)
|
|
- GDP MoM (15/10)
- Manufacturing Production MoM (15/10)
|
|
- India CPI (12/10)
- China CPI (14/10)
|
Chart of the moment - Lula da Lusa
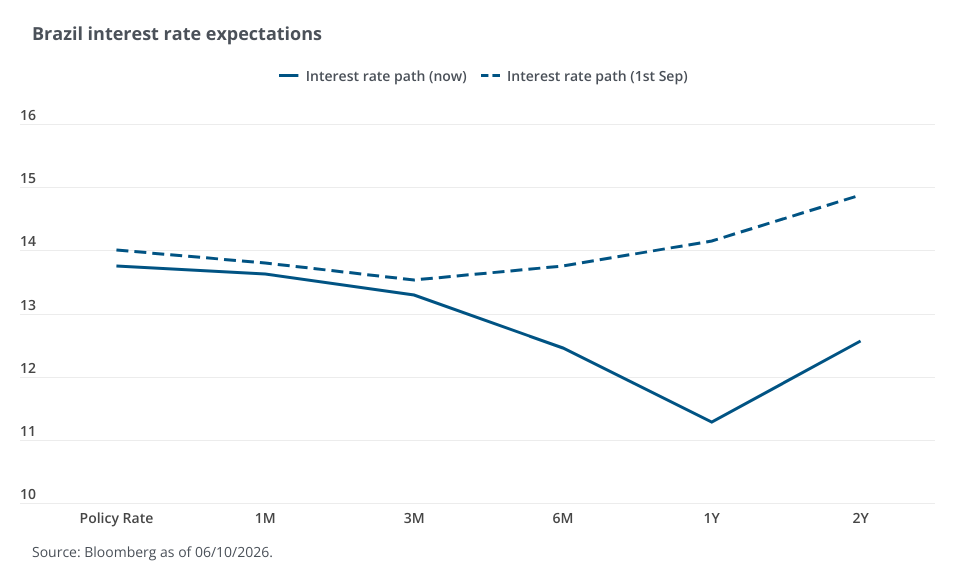
- There was a surprise result in the first round of Brazil’s election, with Flavio Bolsonaro beating President Lula da Silva and becoming the favourite for the second-round runoff.
- Flavio plans significant fiscal reforms to tackle Brazil's fiscal deficit and reduce state involvement in the economy.
- Due to this result, markets have materially revised down their interest rate expectations, with a significant easing cycle now priced in.
- Lower rates should provide tailwinds for domestic demand, credit growth and corporate earnings after several years of restrictive policy.
- Brazil's combination of moderating inflation and still-high nominal rates gives policymakers scope to support growth if economic momentum weakens.