US equities were muted for the week as markets balanced softer labour market data and easing expectations for further Federal Reserve (Fed) tightening against elevated Treasury yields and volatile oil prices. Economic data was generally supportive, with the Fed’s preferred inflation measure rising 3.0% year-on-year in August, below expectations. September nonfarm payrolls showed the economy added just 29,000 jobs, significantly below consensus forecasts of around 90,000.
Elsewhere, Eurozone inflation rose above expectations in September, driven by higher energy prices. UK manufacturing activity remained in expansion territory, while the Reserve Bank of Australia raised rates by 25bps and left the door open to further tightening. In Brazil, right-wing candidate Flavio Bolsonaro emerged ahead in the first round of the presidential election by about 2 percentage points, making him the strong favourite ahead of the runoff at the end of October.
Last week's highlights
 |
- Core PCE (30/09) – Rose 3.0% year-on-year in August, softer than expected.
- ADP Nonfarm Employment Change (30/09) - US private-sector employment rose by 90,000, stronger than expected and indicating resilience in the labour market
- Nonfarm Payrolls (02/10) - US September payrolls rose just 29k versus 90k expected, while prior months were revised down and wage growth cooled.
|
 |
- Eurozone CPI – September Preliminary (02/10) - September Eurozone inflation rose to 3.8% YoY from 3.2% in August, above the 3.6% consensus forecast, driven mainly by higher energy prices.
|
 |
- UK Nationwide House Price Index (30/09) - House prices fell 0.2% MoM in September, with annual growth halved to 0.8%, highlighting continued softness in the housing market.
- S&P Global Manufacturing PMI (01/10) - UK manufacturing activity remained in expansion territory, with the PMI rising to 51.9.
|
 |
- Reserve Bank of Australia Meeting (29/09) - The RBA raised its cash rate by 25bps to 4.60%, signaling ongoing concern about inflation and leaving the door open to further tightening.
- Brazil Election (04/10) - Right-wing candidate Flavio Bolsonaro emerged ahead in the first round of the presidential election by about 2 percentage points.
|
Looking ahead to the week, investors will focus on a range of economic activity data, including the S&P Global PMIs and ISM Services PMI in the US, HCOB PMI releases across the Eurozone, and PMI updates in the UK. Elsewhere, the Reserve Bank of India is due to meet with a rate hike expected.
What's on the radar
|
- S&P Global Services PMI (05/10)
- ISM Non-Manufacturing PMI (05/10)
- FOMC Meeting Minutes (07/10)
|
|
- HCOB Eurozone Services PMI (05/10)
- HCOB Eurozone Composite PMI (05/10)
|
|
- S&P Global Services PMI (05/10)
- S&P Global Composite PMI (05/10)
- RICS House Price Balance (08/10)
|
|
- Reserve Bank of India Meeting (07/10)
|
Chart of the moment - There's a whole other world out there
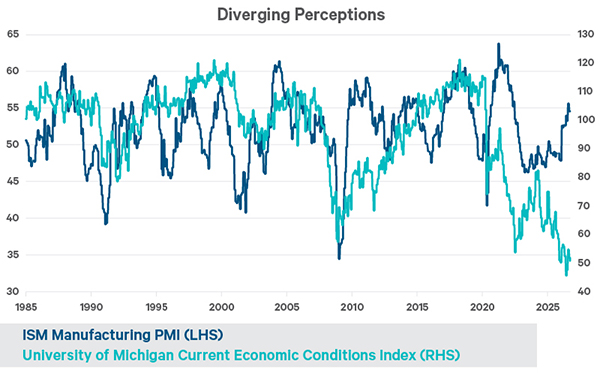
Source: Davy, Bloomberg as of 01/10/2026.
- The Conference Board's poll on Consumer sentiment is unusually weak, with Americans feeling worse than during the Global Financial Crisis and Covid.
- Markets tell a different story with equities near all-time highs and economic growth showing few signs of weakness.
- The gap between consumer confidence and business surveys (ISM manufacturing PMI) is historically unusual.
- Rising living costs, housing affordability and higher prices are likely weighing on households as headline growth stays robust.
- Inequality may be the key explanation: aggregate GDP looks healthy, but many consumers are not experiencing the benefits and remain financially stressed.