US equities moved lower for the week as escalation in the Middle East pushed oil prices higher. US CPI came in at 3.4% for August, potentially locking in a rate hike from the Fed. In Europe, the European Central Bank hiked rates by 25 bps as expected, noting that the “conflict in the Middle East continues to generate inflation pressures”. In the UK, the economy grew by 0.4% in July, beating expectations, supported by stronger services activity.
Last week's highlights
 |
- 10-Year Note Auction (09/09) – Despite a higher auction yield of 4.834%, demand was strong, with a bid-to-cover ratio rising to 2.71.
- Initial Jobless Claims (10/09) – Broadly unchanged (206k), in line with expectations.
- US August CPI (11/09) – Prices rose 0.4% as expected, while core inflation came in slightly higher than forecast at 0.3%.
|
 |
- ECB Interest Rate Decision (10/09) – Raised interest rates by 25bps, as expected, taking the deposit rate to 2.50%.
- German August CPI (10/09) – Increased to 2.9% YoY from 2.8% in July, driven by higher energy prices.
|
 |
- UK July GDP (11/09) – The economy grew 0.4%, ahead of expectations (0.3%), supported by stronger services activity.
|
 |
- Japan Q2 GDP (08/09) – Annualised growth was revised higher from 1.1% to 1.4%, slightly below expectations.
|
This week, the main event will be the Federal Reserve (Fed) meeting on Wednesday with markets now expecting a rate hike following Friday’s inflation data. Fed chair Kevin Warsh has struck a hawkish tone recently, emphasising that the Fed's 2% inflation target is "firm and fixed“. In the Eurozone, inflation data is due out on Thursday, the European Central Bank’s new staff projections sees headline inflation averaging 3.0% in 2026 and 2.5% in 2027. In the UK, the Bank of England will meet and is expected to hold rates steady but could acknowledge increased inflation risks due to higher energy prices. Finally, markets are expecting another rate hike from the Bank of Japan, after holding rates steady in July.
What's on the radar
|
- FOMC Meeting (16/09)
- US Retail Sales (16/09)
|
|
- Eurozone CPI – August (17/09)
|
|
- UK CPI – August (16/09)
- Bank of England Meeting (17/09)
|
|
- Bank of Japan Meeting (18/09)
|
Chart of the moment - Bank for your buck
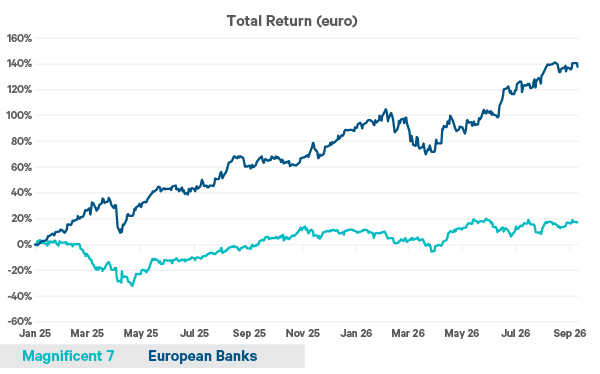
Bloomberg as of 09/09/2026. Total return in euros. The Magnificent 7 refers to Apple, Amazon, Alphabet, Meta, Microsoft, Tesla, Nvidia. Indices used: Magnificent 7 - Bloomberg Magnificent 7 Total Return Index, European Banks - Euro Stoxx Banks Index.
- European banks have produced exceptional returns recently and have become meaningful contributors to European earnings growth.
- Following the Global Financial Crisis (GFC), the banking sector was a major drag on earnings as banks struggled with negative interest rates, tighter regulation and the need to rebuild capital following the GFC and sovereign debt crisis. These forces have now largely reversed.
- Higher margins, improving capital efficiency and healthier bank balance sheets indicate a genuine improvement in fundamentals.
- Overall European earnings growth has recovered strongly this year, with analysts now expecting 20% earnings growth for 2026, after broadly flat growth in 2025.