US equities finished lower for the week, weighed down by AI-related names, as investors continued to question the sustainability of AI-related investment. US inflation surprised to the upside, with headline CPI accelerating to 3.7% in September and core inflation rising to 2.6%. Gasoline prices jumped 9.1% over the month and accounted for more than half of the 0.6% monthly CPI increase. Producer prices were also strong, rising 1.3% MoM and 6.3% YoY, while retail sales increased 0.8% MoM, pointing to continued resilience in consumer demand.
Elsewhere, the picture was mixed. UK GDP grew just 0.1% MoM in August, slowing from 0.4% in July, although production strengthened while services were flat. Inflation pressures also picked up internationally, with India CPI rising to 5.54%, driven by stronger food inflation, while China CPI edged up to 0.9% YoY, although underlying price pressures remained relatively subdued.
Last week's highlights
 |
- CPI September (14/10) - Headline inflation rose to 3.7% YoY, with core CPI at 2.6%. Gasoline prices jumped 9.1% MoM, driving over half of the 0.6% monthly increase.
- Retail Sales MoM (15/10) - rose 0.8% MoM, well above the 0.3% expected, while August was revised up to +1.3%.
- PPI – September (15/10) - surged 1.3% MoM, the biggest monthly rise since March 2022, taking annual producer inflation to 6.3% YoY.
|
 |
- Eurozone Industrial Production (15/10) - fell 0.5% MoM and 1.1% YoY, extending July’s 0.3% monthly decline and signalling continued weakness in the industrial sector.
- German CPI (13/10) - 3.3% YoY, up from 2.9% in August and the highest since December 2023, largely driven by higher energy prices.
- CPI YoY (16/10) - Rose to 3.8%, from 3.2% in August, driven largely by energy inflation of 18.8%. Core inflation was 2.5%.
|
 |
- GDP MoM (15/10) - grew 0.1%, slowing from 0.4% in July. Growth was driven by production, while services were flat and construction fell.
- Manufacturing Production MoM (15/10) - rose 1.2% MoM, with 9 of 13 manufacturing subsectors expanding. Pharmaceuticals (+5.1%) accounted for over half of the monthly growth.
|
 |
- India CPI (12/10) - September inflation rose to 5.54% YoY from 4.83%, slightly above the 5.4% forecast, driven by a sharp rise in food inflation.
- China CPI (14/10) - Inflation edged up to 0.9% YoY from 0.8% in August, but undershot the 1.0% expected; CPI rose 0.2% MoM, with underlying consumer demand remaining subdued.
|
Looking ahead, attention turns to China’s Q3 GDP and central bank meeting, alongside the UK labour market and CPI data. In Europe, German ZEW sentiment and Eurozone PMIs will provide an update on growth momentum, while US jobless claims and preliminary PMIs will be watched for signs that activity remains resilient despite renewed inflation pressures.
What's on the radar
|
- Initial Jobless Claims (22/10)
- S&P Global Services and Manufacturing PMI (23/10)
|
|
- HCOB Eurozone Composite PMI (23/10)
- ZEW German Economic Sentiment (20/10)
|
|
- CPI YoY (21/10)
- UK Labour Market Report (20/10)
|
|
- China GDP YoY Q3 (19/10)
- Chinese Central Bank Meeting (20/10)
|
Chart of the moment - Capexcess?
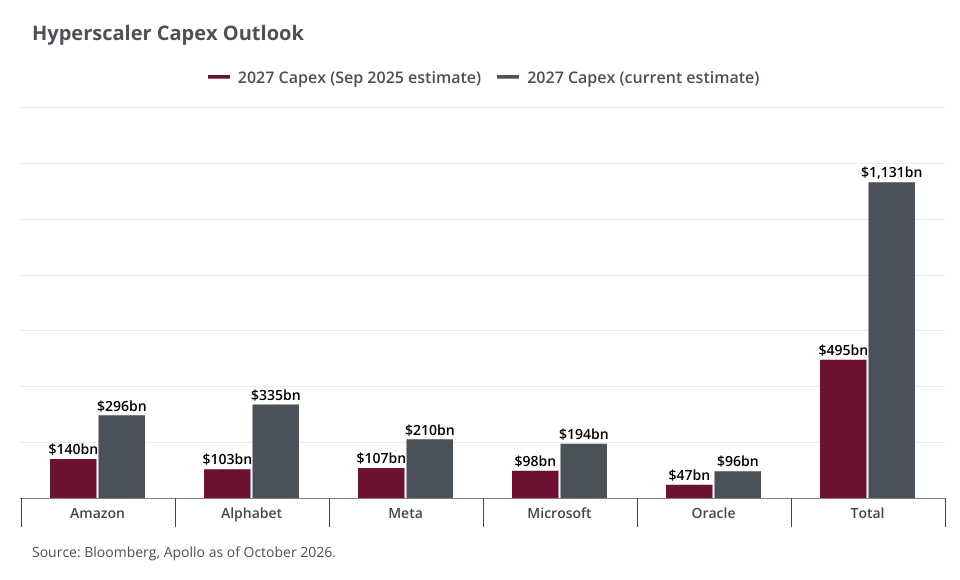
- Hyperscaler capex expectations have risen sharply, with combined 2027 spending estimates more than doubling from $495bn to $1.13tn over the last 12 months.
- As free cash flow has come under pressure, companies have increasingly turned to alternative funding sources, including equity issuance, investment-grade debt and private capital.
- The US midterms are seen as a potential threat to the AI buildout, as rising odds of a Democratic sweep have led to concerns over tighter regulation and a less supportive policy backdrop for large-scale AI investment.